Does My Insurance Cover a Roof Replacement in New York? [2026 Update]
Determining whether your homeowner property policy fully funds a comprehensive roof replacement in New York is a vital financial milestone when dealing with sudden exterior deterioration or storm impact. Navigating corporate property insurance frameworks across Long Island requires a clear, analytical look at policy exclusions, mandatory regional deductibles, and direct physical evidence criteria. Because standard catastrophic weather events can rapidly degrade underlying structural components, executing a timely property claim assessment prevents localized structural decay from causing extensive interior ceiling failures.
Successfully securing approved funding for a professional roof replacement in New York depends heavily on proving sudden, accidental wind or hail impact rather than routine structural aging. Many property owners make the mistake of postponing their structural filings until an active attic leak ruins their home’s interior sheetrock, which often leads to claim denials based on neglect. To preserve your hard-earned asset value, you must actively team up with a certified expert to map out your physical storm evidence immediately. In this professional guide, we will break down the essential milestones of navigating regional insurance claims.
Table of Contents
- Understanding Covered Perils vs. Routine Wear in Long Island
- The Architecture of a Successful Insurance Claim Filed in 2026
- Navigating Hurricane and Windstorm Deductible Structures
- Meticulous Field Evidence and Photo Documentation Standards
- Understanding Replacement Cost Value vs. Actual Cash Value
- Managing the Supplement Process for Hidden Wood Rot Repair
- Frequently Asked Questions
- Maximizing Your Protection with Certified Technical Support
Understanding Covered Perils vs. Routine Wear in Long Island
The primary baseline for any property coverage evaluation rests on the specific root cause of your system’s underlying damage. To get an approved roof replacement in New York, the damage must be the direct result of an official covered peril, such as an intense seasonal coastal storm, fallen tree limbs, or severe lightning impacts. Insurance companies explicitly design their standard homeowner policies to safeguard against sudden accidents rather than normal material degradation.
If your asphalt shingle system is simply near the end of its natural lifespan and suffers from progressive granule thinning, your policy will not cover the restoration costs. Distinguishing between sudden storm damage and routine wear during your inspection is the absolute best way to set accurate expectations for your household budget. Proactively checking your outer shingle slopes after local storms ensures you catch covered issues early.
The Architecture of a Successful Insurance Claim Filed in 2026
The operational process of navigating an active property claim requires following structured legal steps to prevent technical adjustor delays. Homeowners seeking a permitted roof replacement in New York should follow this verified timeline:
| Operational Phase | Primary Technical Actions Required | Key Structural Outcomes |
|---|---|---|
| Damage Discovery | Schedule an emergency physical inspection following a local storm | Identifies hidden wind uplift fractures early |
| Official Filing | Submit a detailed photo log and field assessment to your adjuster | Establishes the date of loss within policy guidelines |
| Adjuster Meeting | Meet the insurance field representative on site with your contractor | Ensures all structural damage points are noted accurately |
To see how our certified technicians assist local homeowners during these critical structural assessments, take a quick moment to look through our Aaron Roofing Home Page. Following a professional, structured plan maximizes your chances of securing a full project approval.
Navigating Hurricane and Windstorm Deductible Structures
Home insurance policies in our coastal region often include specialized windstorm deductibles that differ significantly from standard flat-rate property deductibles. When filing for a roof replacement in New York after a coastal storm, your out-of-pocket costs are often calculated as a fixed percentage of your home’s total insured structural value, usually ranging from two to five percent.
Understanding these unique percentage rules is essential for managing your personal repair budget without unexpected financial surprises. Our administrative team reviews your policy papers closely to help clarify exactly what your out-of-pocket share will be before any crew begins work on your home. To explore our full gallery of certified storm restorations across local neighborhoods, feel free to visit our corporate Aaron Roofing Gallery. Clarifying your financial parameters upfront keeps your project moving smoothly.
Meticulous Field Evidence and Photo Documentation Standards
The clear ultimate deciding factor for any regional property coverage approval is providing undeniable physical proof of damage. Insurance adjusters will not approve a full roof replacement in New York based on vague ground-level descriptions or verbal assumptions. Your submission packet must include high-resolution, time-stamped photos showing torn shingle tabs, exposed underlayment sheets, and severe hail impact marks.
Our field inspectors utilize advanced diagnostic tools to safely capture clear close-up images of damaged ridge caps and compromised valley flashings. Providing this detailed technical proof leaves no room for adjusters to dispute the true extent of your storm damage. To learn more about our company’s strict inspection methods, feel free to read our About Aaron Roofing Page. Presenting solid, organized evidence speeds up your claim processing timeline dramatically.
Understanding Replacement Cost Value vs. Actual Cash Value
How your policy calculates depreciation plays a massive role in the final payout you receive for your exterior home upgrade. If your policy features Replacement Cost Value (RCV) coverage, your insurance provider will fund a full roof replacement in New York by paying out the actual current market cost to rebuild your system, minus your deductible. This ensures your personal household budget is fully protected from rising material costs.
Conversely, an Actual Cash Value (ACV) policy deducts significant value based on the age and wear of your old roof shingles, meaning your payout will be lower. To review current national building safety frameworks regarding structural wind ratings and storm resilience, homeowners can reference official guidelines from FEMA. Knowing your specific policy structure helps you plan your home investment with total confidence.
Managing the Supplement Process for Hidden Wood Rot Repair
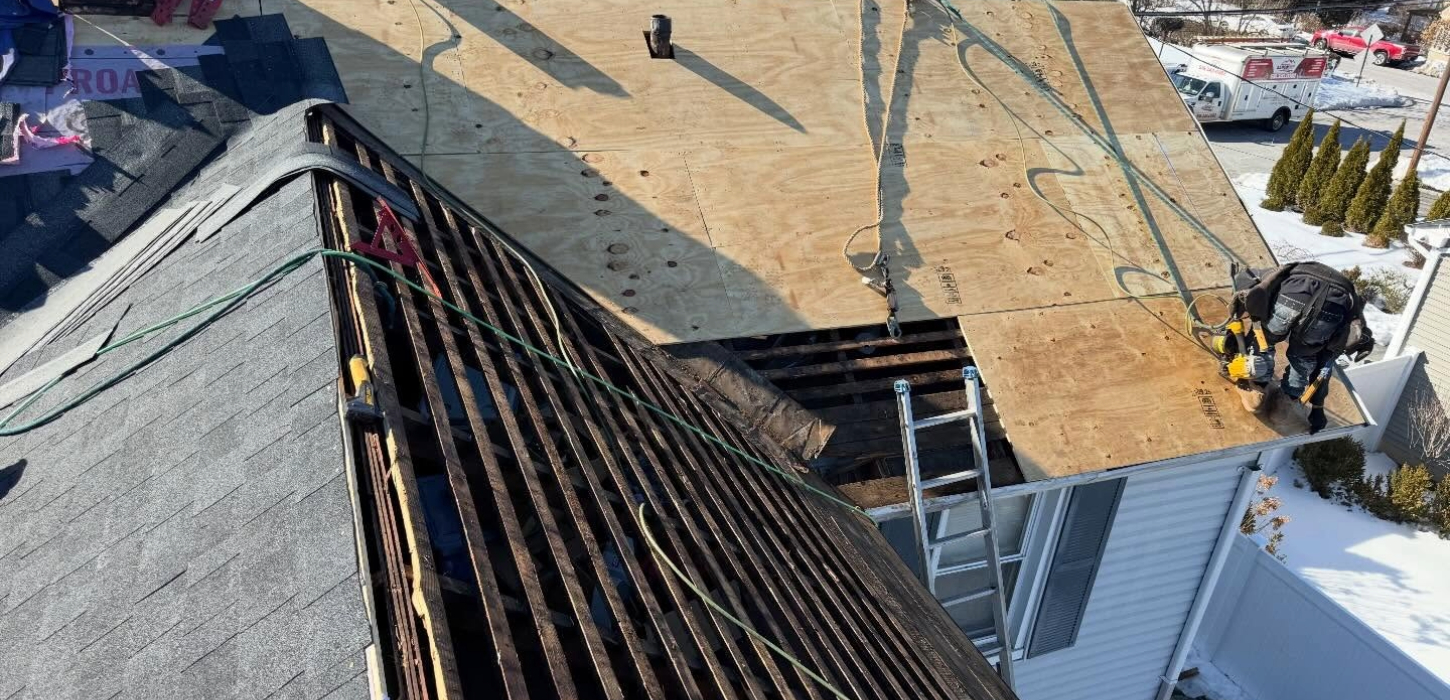
A common challenge during a storm restoration occurs when field crews uncover hidden structural damage after removing the old shingles. When executing a roof replacement in New York, we often find rotted plywood decking or cracked structural rafters that were invisible during the initial adjustor walk. If these items were left off the original insurance check, a supplement must be filed immediately.
Our experienced project managers document these newly exposed issues instantly with photos and upload an official cost supplement directly to your claim adjuster. This ensures the insurance company funds the extra structural repairs needed to deliver a safe, long-lasting installation. To review our complete range of certified repair capabilities, feel free to visit our primary Roofing Services Long Island page. We manage every step of the paperwork so your home is repaired correctly without taking shortcuts.
Frequently Asked Questions
Can a local roofing company legally pay for my insurance deductible?
No, absolutely not. It is completely illegal for any contractor to pay, waive, or rebate your property insurance deductible under New York state law. Any team offering to hide your deductible is engaging in insurance fraud, which can quickly void your entire claim and cause major legal issues.
How long do I have to file an official claim after a storm passes my home?
Most standard property policies require you to file an official claim within one year from the exact date of the storm event. However, we strongly advise arranging a professional inspection immediately after a storm to ensure you document the damage before normal seasonal wear complicates your claim.
What happens if my insurance provider denies my initial claim for damage?
If your initial filing is denied, you have the legal right to request a re-inspection with a different field adjuster or file an official administrative appeal. Providing a highly detailed, line-item photo log from a certified local expert is the best way to get a denial reversed.
Will my monthly insurance premiums go up if I file a storm damage claim?
In New York, insurance providers are generally prohibited from raising your individual premium rates for filing a single claim caused by natural weather events or acts of nature. Your rates are typically adjusted based on broad regional risk factors rather than your individual storm history.
How long does the entire storm restoration process take from start to finish?
The initial claims review and approval process can take anywhere from two to six weeks depending on adjuster availability. Once your insurance claim is officially approved and raw materials are delivered, our expert field crews usually complete the actual installation within one to two days.
Maximizing Your Protection with Certified Technical Support
Navigating a property insurance claim requires clear technical evidence, a solid understanding of your policy guidelines, and detailed photo documentation. By focusing on proving sudden storm damage, verifying your RCV parameters, and handling hidden wood supplements properly, you can secure the full funding needed for a roof replacement in New York. Partnering with a certified local expert ensures your home is rebuilt to the highest safety and quality standards.
Our administrative team is here to guide you through the inspection and documentation phases smoothly. When you are ready to evaluate your shingle system and compile an official, expert damage report for your home, reach out to our office. Contact Aaron Roofing Corp today to schedule your comprehensive storm damage assessment and let our certified team guide your roof replacement in New York with total peace of mind.